Showing posts with label Frugal Panda. Show all posts

Sunday, December 13, 2015

Red Kidney Bean Aquafaba Meringues

My dad was, and probably still is, the very opposite of wasteful. He had a bucket in the shower to collect the cold water before you got in, and used it later for flushing the toilet. He'd put on more clothes, rather than turning on the heater. Food scraps would be eaten where possible, or else taken out to compost.

It pains me just as much to throw food away, which is why I have experimented with eating carrot tops, and cooking with sourdough starter which no longer smelt right. The other night, I made a chili using tinned red kidney beans, and suddenly recalled reading about a recent discovery involving the bean liquid: named aquafaba, it turns out the thick and frothy brine can be whipped up just like egg whites!

While chickpea water has the most neutral flavour, I decided to try making meringues with the red kidney bean liquid I had on hand. What started out as a reddish-brown gloop became paler as it aerated in the food processor.

Red kidney bean liquid before whipping.

The original recipe from Goose Wohlt only calls for 1/2 cup sugar and the liquid from one can of beans, but I didn't seem to be able to get the ingredients to form stiff peaks, so I added cream of tartar and vanilla as well, based on the recipe from Kids with Food Allergies. It took me half an hour to realise I had left the food processor blades in, before switching to the whisk attachment.

Mixture became pale and thick after whipping.

Using the egg whisk gave a much fluffier result, but I still couldn't get the mixture to form stiff peaks, and my food processor was getting hot. I went ahead and spooned the whipped concoction onto baking paper and put it in the oven anyway.

Any peaks disappeared quickly.

Depending on which recipe you pick, you are supposed to bake the meringues at 100C/200F for 1.5 hours, 120C/250F for 40 minutes, or use a mix of temperatures. I baked mine at 100C for 1 hour, then turned off the oven and left them inside overnight.

Baking the aquafaba meringues.

Because I didn't put my meringues into an airtight container in a timely manner, I baked them again the next day to dry them out properly. You need to wait for them to cool first, not just to avoid the moisture being trapped in the storage box, but also because they are soft and sticky while warm—I tried pulling one off the baking paper straight away and the bottom stuck, but those which I removed after cooling slid off effortlessly.

Aquafaba meringue stuck to baking paper while warm.

I'm not sure why the surface of my meringues seemed to have little circles on them, but the result was light and crunchy. Overall, I think they were actually closer to hokey pokey than meringues, because they stuck to your teeth when you ate them, and there seemed to be a bit of malt or caramel flavour.

The aquafaba meringues were light and crunchy.

Breaking the crunchy bits over fresh strawberries and coconut yoghurt greatly reduced the teeth-sticking, and made a tasty vegan and gluten free dessert.

Aquafaba meringues with strawberries and coconut yoghurt.

Apparently, aquafaba can be used to make a variety of different (vegan) dishes, such as:

You can also use it as an egg substitute (including as egg wash) by replacing each egg in many recipes with 3 Tbsp aquafaba.

I was pleased with how my meringues turned out, and amazed by their transformation from a slimy liquid into light and crunchy pillows. I would be tempted to retry these with chickpea brine, and see how aquafaba works in savoury recipes as well. No more tipping bean liquid down the drain—my dad would be pleased!


This post is part of Our Growing Edge, a monthly blogging event aimed at inspiring us to try new things. This month, it is hosted by Jazzmine from Dash of Jazz, with a theme of Nostalgia.

Friday, February 28, 2014

Homemade Loquat Liqueur

A relative has a loquat tree on their property. Several months ago, it bore fruit, and we were gifted with a large number of the sweet, aromatic spheres.

Loquats on the tree.
It was the first time we had ever tried loquats, and I thought they were cute, held together by chubby, furry stems.

Ripe loquats.
There wasn't much flesh in each fruit, as a lot of the space was taken up by the seeds in the centre, but what there was was delicious at the right level of ripeness.

Inside a loquat.
As we had more than we could eat, I tried to make dried fruit out of most of them, putting the cut halves into the barely warmed oven over a number of days.

Loquat halves laid out for drying.

Sadly, that was a waste both of effort and delicious fruit, as even days later, the pieces were still not dry (perhaps I should have turned the oven on for longer). Pricking the skins with a fork and turning some of the pieces over did not help much either. Not only that, the orange rounds had oxidised and turned black, and the beautiful fragrance of the fresh fruit was no longer there.

Unattractive partially-dried loquats.
I put the shrivelled-up, leathery and not very sweet loquat pieces into a jar, thinking I could bake them into something perhaps, but by the time I remembered them, they had started to grow mouldy. Epic fail.

All those loquats left me with something else on my hands. I did not want to simply throw the seeds away, and when I discovered that people made loquat liqueur with them, I decided to give it a go as well. I haven't had success with brewing in the past, but loquat liquer didn't require any skills or special equipment. This was really only going to be a vodka infusion.

Loquat seeds.
Possible Poison?

While searching for recipes, I came across some pretty scary sounding advice out there. For instance, a post  by bpotter on the GardenWeb forum claimed the seeds contain a dangerous level of cyanide compounds:
Most of the stone fruit (peaches, apricots, plums) are in the rose family and loquats (at least 2 different species I know of) are members. Their pits contain dangerous levels of cyanide compounds. Our native holly-leaf cherry was used by the native Chumash people as a source of food and they knew that they had to leach out the poisons from the pits by repeated soakings and boilings before they made a mush out of them.
Others, such as Susan Lutz at Zester Daily, point out that while the pits contain toxic substances, there is not enough to worry about:
I put in a call to professor Jules Janick, director of the Indiana Center for New Crops and Plant Products at Purdue University. He’s not only the co-editor of “The Encyclopedia of Fruits and Nuts,” he is also a kind and understanding voice of reason. Janick told me that loquat seeds are indeed toxic, but then so are the seeds of apples and pears. To put things into perspective, Janick said, “If you ate 3 pounds of them, then it might be a problem.” He also reminded me that the bitterness of the seeds would stop someone from eating them pretty quickly. I realized that my daughter was at far greater risk for choking on a loquat seed than being poisoned by its chemical components.
Then there are those who deliberately eat the seeds out of the belief that it can help combat cancer. A modified form of the chemical amygdalin found in the pips (also in the kernels of apricots, peaches, cherries, and almonds) is marketed as Laetrile, although there is no proof that it is effective against cancer.

I wasn't able to find out how dangerous loquat seeds were, but I did come across some tables for other foods. This came with the warning that "cyanogen levels can vary widely with cultivar, climatic conditions, plant part and degree of processing."

Food Sources of Cyanogenic Glycosides and Amount of Hydrogen Cyanide (HCN) Produced
PlantCyanogen content  (mg HCN/kg) Major cyanogenic glycoside present
Giant taro (Alocasia macrorrhizos) – leaves29-32Triglochinin
Nectarine (Prunus persica var nucipersica) – kernel196-209Amygdalin
Flax (Linum usitatissimum) – seed meal360-390Linamarin, linustatin,
neolinustatin
Peach (Prunus persica) – kernel710-720Amygdalin
Plum (Prunus spp.) – kernel696-764Amygdalin
Apple (Malus spp.) – seed690-790Amygdalin
Apricot (Prunus armeniace) – kernel785-813Amygdalin
Cassava (Manihot esculenta) – root15-1000Linamarin
Sorghum (Sorghum vulgare) – leaves750-790Dhurrin
Whole Sorghum2500Dhurrin
Lima beans (Phaseolus lunatus) 100-3120Linamarin
Bitter almonds (Prunus dulcis)2500-4700Amygdalin
Bamboo (Bambusa arundinacea) – young shoots100-8000Taxiphyllin

The numbers above don't entirely agree with a New York Times Q&A piece, which quotes Dr. Margaret Dietert, associate professor of biology at Wells College, Aurora, N.Y., in saying that "13 to 15 raw peach pit kernels would get you into the lethal range for adults", while the level of cyanogen in apple seeds is "about a quarter as much as peach pits for the same weight".

Meanwhile, food scientist consultant John Fry has this to say in The Naked Scientists, again about apple pips:
You need about 1 milligram of cyanide per kilo of body weight to kill a human being. Apple seeds contain about 700 milligrams of cyanide per kilo, so about 100 grams of apple seeds should be enough to dispatch a 70-kg adult human, but that’s an awful lot of apple cores even if you don't eat the rest of the apple first. In addition, the seeds would have to be pretty finely crushed to let the enzymes get to the amygdalin at all. All in all, you're safe eating the occasional apple core. I've done it for years. Just don't try eating a bowl of freshly crushed apple pips.
I still had some reservations about eating anything made with loquat seeds, but seeing that people even use the roasted seeds as a coffee substitute helped to allay those fears.

Making Loquat Liqueur

Although loquats come from China, they are also common in other countries such as Italy, where they are called nespoli. A liqueur made from the loquat seeds is called nespolino, similar to nocino made from unripe green walnuts, and amaretto made from apricot kernels or almonds.

I roughly followed the directions from Gardenista, which went like this:
Rinse seeds and set out in the sun to dry for two weeks.
The classic Italian recipe calls for grain alcohol, but a neutral vodka works as well. To the pits, add one whole vanilla bean and 1/4 of a lemon rind, pith removed. Let this sit in the sun for about a month. Add a sugar simple syrup to taste, and then let it sit for another two weeks.
I'm not sure why the seeds should be set out in the sun to dry. Another recipe for loquat grappa omits this step. Perhaps it helps to intensify the flavour?

Loquat seeds with lemon peel in vodka.

After a couple of weeks of soaking, I noticed that the liquid level had dropped in my jar. Did the alcohol evaporate away somehow, or did it get absorbed into the seeds? I topped up with more vodka, and noticed a delicious almond and floral fragrance already.

Reduced level of liquid.
After a couple more weeks, the liquid level had dropped again, but this time, instead of topping up with more alcohol, I made a sugar syrup and poured that in. I promptly forgot about it for another month, even though I had meant to take the seeds out after two more weeks. I don't think that did any harm though, seeing as there are recipes that call for soaking the seeds for up to six months.

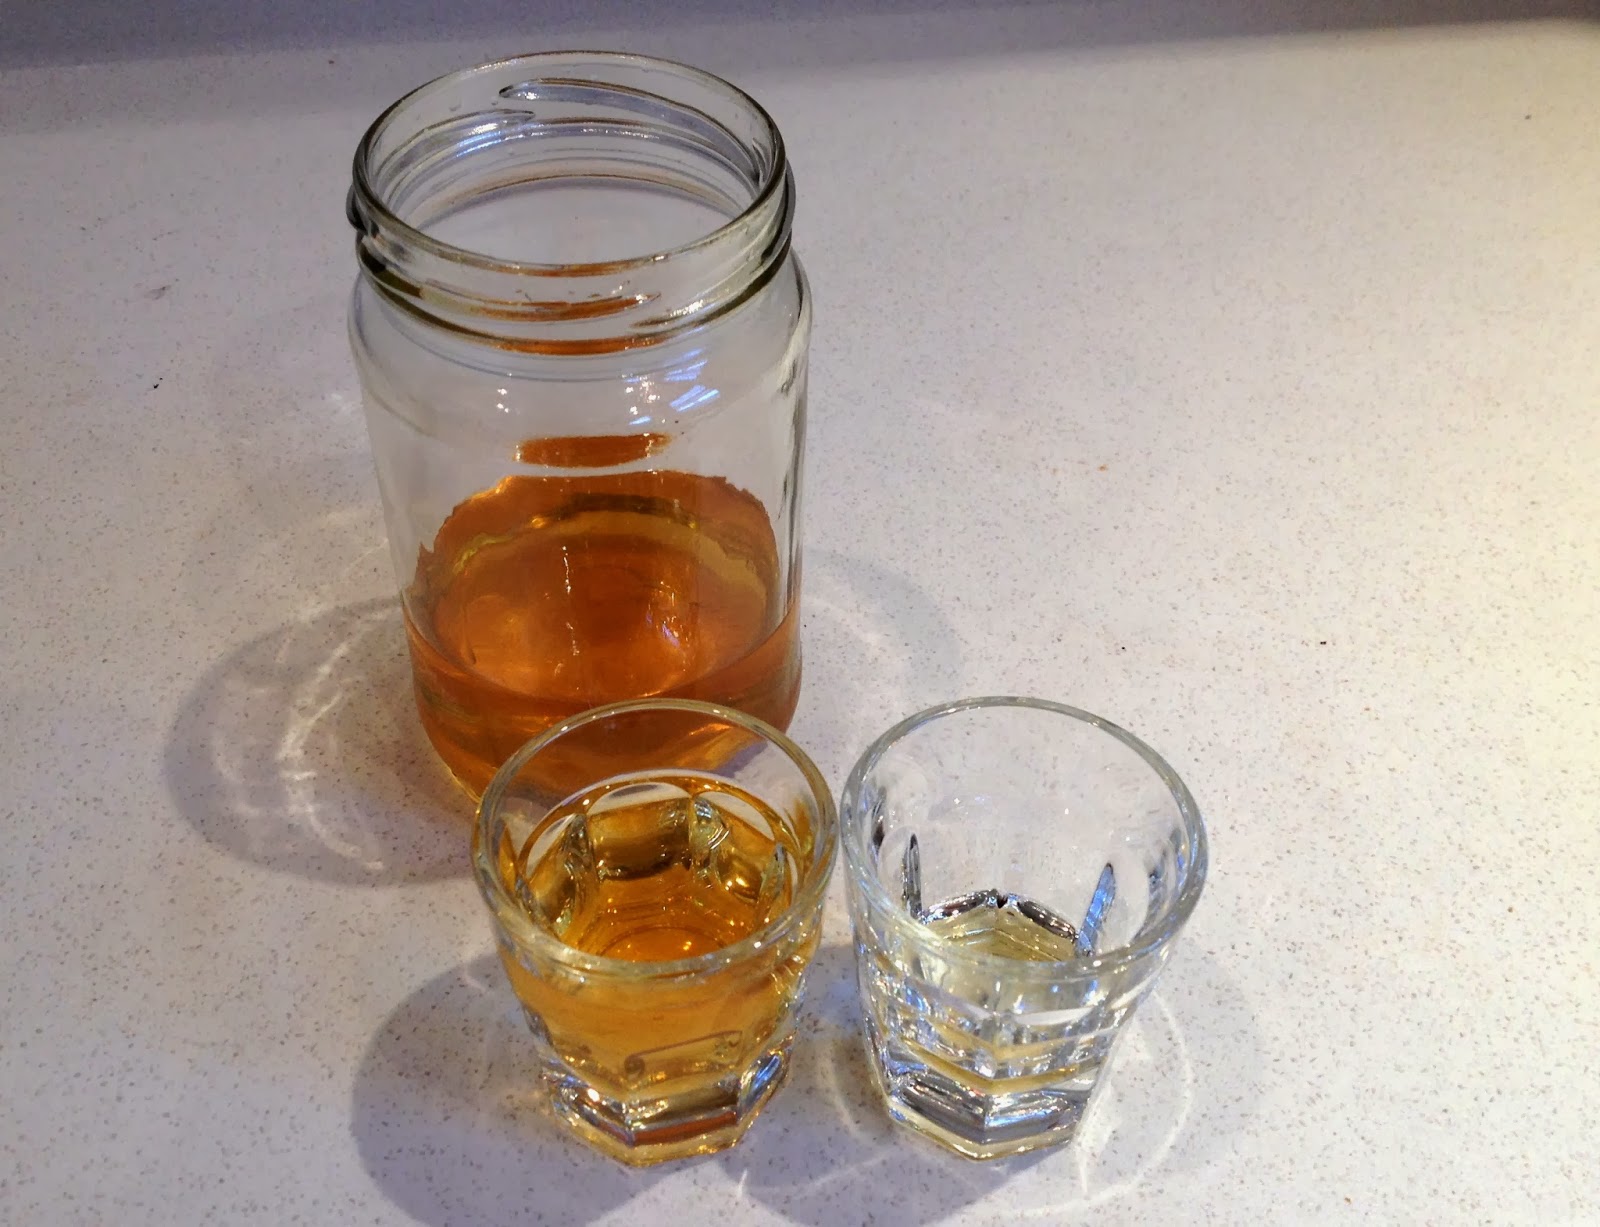
Fragrant end product.
And the end product? The almond flavour was more pronounced, and overlaid with a pungent one that you might poetically describe as "formaldehyde". According to the PICSE website, amygdalin "in the presence of water and the enzyme beta glycosidase (Emulsin) releases glucose, hydrocyanic acid (Prussic acid) and benzaldehyde... It is the Benzaldehyde is responsible for the bitter astringent taste while the Hydrogen Cyanide is responsible for the almond aroma." Interesting and complex to your senses then, but not something that I will be having large amounts of.


This post is part of Our Growing Edge, a monthly blogging event aimed at inspiring us to try new things. This month, it is hosted by Kindra, from California Cavegirl Kindra.

Wednesday, January 29, 2014

Eating Carrot Greens

I don't like to throw things out. Leftover cakes are given away or stashed in the freezer. Aging vegetables are turned into soup. I will eat something, even if I don't feel like it, to stop it going into the bin.

When I saw carrots for sale at the supermarket, complete with greens attached, I naturally had to find out if the tops could be used for something. I came across a recipe for sauteed carrot greens, which sounded more than just edible. I mean, the writer even took discarded carrot greens from other customers at the market while concealing her excitement.

Bunch of carrots from the supermarket.
It turns out that the warning "the stems are pretty tough and toothsome even when cooked" was not an understatement. These greens were really fibrous and difficult to chew.

Swinging the balance towards vegetables.
Also, what the post neglected to mention was that these leaves had a pungent flavour and odour, very similar to the Asian vegetable known as tong ho (茼蒿) or garland chrysanthemum.

Deceptively innocent-looking carrot greens.
I enjoyed the bitter flavour—that's what I look for in leafy greens—but next time, I would save carrot tops for the stock pot, rather than risk pulling a muscle in my jaw.


This post is part of Our Growing Edge, a monthly blogging event aimed at inspiring us to try new things. This month, it is hosted by Louise from Crumbs and Corkscrews.

Monday, May 20, 2013

Money Matters: OneSmart's New Fees and Terms

Up until recently, I have been positive towards using Air New Zealand's OneSmart card while travelling overseas.  As late as in September last year, I have tested making transactions in a foreign currency on my Visa credit card and on my OneSmart card on the same day, and found the rates from OneSmart to be more favourable.  Lately, however, OneSmart's exchange rates have taken a turn for the worse, and for purchases I made earlier this month, it actually cost me less money to use my normal credit card for payments in-store. [Added 23 May 2013: Just to clarify, the OneSmart was still better for getting cash out at overseas ATMs, due to the high fees my bank charges to use my debit/credit card that way.] To add insult to injury, I discovered only two weeks ago that OneSmart's fees and terms are changing - starting from tomorrow! The most inconvenient changes for me are that:
  1. only three overseas ATM withdrawals per month will now be free
  2. you can no longer escape fees while leaving money in your OneSmart account indefinitely, just by making sure you have it all in foreign currencies, and making a tiny transaction every three months (though this is softened by the fact that the Monthly Account Fee has been reduced)
Of course, I was not at all impressed.  And I was worried for all the people out there who might not know about the changes.  After all, I only found out because I happened to log in to my OneSmart account.  You might also have found out if you happened to read one of the major national newspapers in detail a week ago, on 14 May.  Otherwise, there was nothing.  No letter in the post, no email advising of the changes. This, despite an Airpoints newsletter being sent out just two days ago, with the following opening paragraph:


That's right, this newsletter "which has been designed to bring you up to speed on any programme, partner, schedule or business changes we think you need to hear about" didn't have a single thing to say about upcoming changes to the OneSmart fees schedule and terms and conditions!

[Added 21 May 2013:
Despite this outrage, I have to say that there is a pretty neat feature being introduced at the same time: a Virtual Card which "means a 16-digit MasterCard card number, security code (CVC2) and expiration date that is different from your Physical Card and can be used to access your OneSmart Account. A Virtual Card can be used for online and telephone transactions only."
This isn't much use if you mislay your OneSmart card when you want to get cash out, but it is reassuring to know that your real number is safe if your virtual number used online has been compromised. If only I had a virtual card for my normal credit card too!
Information about a Virtual Card on the terms and conditions page.
]

Out of interest, how did you first find out about these changes?  I've created a poll which you will find on the right (unless you are reading this post in the mobile view).

[Added 27 June 2013: The poll is now over. The results are as follow:

I logged in to my OneSmart account  5 (29%)
I looked on the OneSmart website  2 (11%)
I read the newspaper on 14 May  0 (0%)
I read Nom Nom Panda's blog  9 (52%)
I read some other blog  0 (0%)
My friends told me  1 (5%)
I noticed I was charged a fee  0 (0%)

]

Saturday, April 27, 2013

Money Matters: A Snapshot Comparison of Currency Exchange Rates

A couple of readers have recently pointed out that the exchange rate of Air New Zealand's OneSmart card is not as good as it used to be. I decided to take a look at how it compares with banks and other travel card options these days. [Added 8 May 2013: I also just noticed yesterday that the OneSmart fees schedule is changing  from 21 May, so have added a column showing the changes in the last table.] [Added 22 May 2013: And vented my displeasure at the lack of communication about the changes.]

Exchange Rates: an Unfair Comparison

In the table below, I have taken the exchange rates from the various websites at around noon on Thursday. I have left out rates for international money transfer, as that requires you to have a bank account in another country. I have also not considered Western Union rates, as their pre-paid cards do not appear to be available in New Zealand, and apart from being the favoured form of payment by scammers, I assume you would also need to have a foreign bank account, or go out of your way to visit an agent at your destination country.

I have highlighted the best exchange rate for each currency in green below.  These are rates for buying foreign currency with your NZD at the major organisations, and do not take into account any commissions or withdrawal fees which may be charged.

One Smart ANZ ASB BNZKiwibank Travelex TSB
25 April, ~12:05p.m. 25 April, 11:59am 25 April, 12:06p.m. 24 April, 16:42pm 25 April, 
12:03pm
24 Apr, 
11:30am
24 Apr,
time not stated
One Smart
Cash
Cash
Cash
Cash
Loaded™ for Travel
Cash (Online)
Cash Passport
Cash
Cash Passport
AUD
Australian Dollars
0.7959 0.8128 0.8109  0.8139 0.8076 0.8162 0.806 0.806 0.8112 0.7962
GBP
Great Britain Pounds
0.5353 0.5458 0.5446  0.5454 0.5424 0.5465 0.5366 0.5366 0.5445 0.5305
USD
United States Dollars
0.8177 0.8344 0.8309  0.8325 0.8294 0.8364 0.8253 0.8253 0.8322 0.8208
JPY
Japanese Yen
81.3450 82.84 82.2535  82.37 82.0470 82.6479 81.1824 81.1824 82.6786 79.6696
EUR
Euros
0.6282 0.6395 0.6367  0.6378 0.6352 0.6398 0.628 0.628 0.6364 0.6226
CAD
Canadian Dollars
0.8383 0.8579 0.8541 0.8485 0.8534 0.8347 0.8347 0.8547 0.8285
AED
United Arab Emirates Dirham
 2.9552

2.7969 2.5459
ARS
Argentine Pesos
3.8538
BRL
Brazilian Real
1.5452
CHF
Swiss Francs
0.7921 0.7833  0.783 0.7786
0.7847
CNY
Chinese Yuan
 4.8805 4.7814
4.7659 4.6691
DKK
Danish Krone
4.7104 4.7282  4.7547 4.7367
4.7462
EGP
Egyptian Pounds
5.1345
5.0377
FJD
Fijian Dollars
1.4598 1.4534  1.4419 1.4490
1.4237 1.4772
HKD
Hong Kong Dollars
6.3486 6.4950 6.4419  6.4433 6.3660 6.4051 6.2393 6.2393 6.4794 6.2324
IDR
Indonesian Rupiah
7664
.0373

7153
.8364
7393
.4198
INR
Indian Rupee
44.3985 41.1603 40.8478 42.4691 43.6899
KRW
Korea (South) Won
 901
.57
841
.0558

865
.1645
819
.1501
MYR
Malaysian Ringgit
 2.4008 2.3915
2.3831 2.349
NOK
Norwegian Krone
4.8963  4.9071 4.8864
4.9068
PGK
Papua New Guinea Kina
 1.6970

1.5628 1.5783
PHP
Philippines Pesos
33.801 32.8944
31.5497 34.0472
SEK
Swedish Krona
5.4399 5.4798  5.5111 5.4419
5.4723
SGD
Singapore Dollars
1.0157 1.0387 1.0269  1.0292 1.0223 1.0314 1.0052 1.0052 1.0351 0.9965
THB
Thailand Baht
23.7798 23.3873  23.50 23.1032 23.3298 22.2673 23.7778
TOP
Tongan Pa’anga
1.3449  1.3457 1.3265
1.2683 1.2796
TRY
Turkish Lira
1.3627
1.3119
TWD
Taiwanese New Dollars
22.2885
24.2543
VND
Viet Nam Dong
15631
.8624

13956
.5145
VUV
Vanuatu Vatu
73.5993
70.0811 71.5479
WST
Samoan Tala
1.8135 1.7792  1.659 1.7601
1.6578 1.6851
XPF
French Polynesian Francs
74.97 74.9845  75.00 71.0793 73.2717
ZAR
South African Rand
7.5299 7.5929  7.6517 7.4484 7.4606 7.1148 7.6647

As Thursday was a public holiday (ANZAC Day), some of these rates have not been updated since the day before. I therefore ran the numbers again yesterday morning, just before 8:30am.  The Travelex and TSB websites did not display refreshed numbers until later in the day, so to avoid using the same data as in the table above, I used rates from a later time.  It's also worth pointing out that I was not able to get all the rates at the same time for OneSmart, because I was viewing each currency manually.  By the time I had gone through the other currencies and checked HKD again, for instance, 1 NZD could be converted to 6.3685 HKD, rather than the 6.3696 HKD listed in the table below, which was from just a couple of minutes earlier.

One Smart ANZ ASB BNZKiwibank Travelex TSB
26 April, ~8:25am 26 April, 8:24am 26 April, 08:29am 26 April,  08:17am 26 April, 
8:28am
26 Apr, 
11:30am
26 Apr,
time not stated
One Smart
Cash
Cash
Cash
Cash
Loaded™ for Travel
Cash (Online)
Cash Passport
Cash
Cash Passport
AUD
Australian Dollars
0.7968 0.8141 0.8145  0.817 0.8076 0.8168 0.8134 0.8134 0.816 0.8021
GBP
Great Britain Pounds
0.5316 0.542 0.5423  0.5428 0.5424 0.5426 0.5363 0.5363 0.5419 0.5306
USD
United States Dollars
0.8204 0.837 0.8383  0.8389 0.8294 0.8387 0.8351 0.8351 0.8393 0.829
JPY
Japanese Yen
81.51 83.04 82.9395  82.97 82.047 82.8247 82.1944 82.1944 83.3479 80.5912
EUR
Euros
0.6307 0.6421 0.6416  0.6422 0.6352 0.642 0.6353 0.6353 0.6413 0.6317
CAD
Canadian Dollars
0.8372 0.8567 0.8565  0.8536 0.8485 0.8521 0.8401 0.8401 0.8564 0.832
AED
United Arab Emirates Dirham
 2.978 2.8301 2.5788
ARS
Argentine Pesos
3.9007
BRL
Brazilian Real
1.5475
CHF
Swiss Francs
0.7926 0.789  0.7887 0.7786 0.7909
CNY
Chinese Yuan
 4.9119 4.7814 4.8161 4.7225
DKK
Danish Krone
4.7295 4.7651  4.7885 4.7367 4.7826
EGP
Egyptian Pounds
5.1345 5.099
FJD
Fijian Dollars
1.4642 1.4658  1.4498 1.449 1.4373 1.48
HKD
Hong Kong Dollars
6.3696 6.5152 6.4991  6.4935 6.366 6.4229 6.3137 6.3137 6.535 6.2958
IDR
Indonesian Rupiah
7664
.0373
7233
.789
7479
.0676
INR
Indian Rupee
44.6721 41.1603 40.7135 42.8084 44.0426
KRW
Korea (South) Won
 902
.09
841
.0558
869
.2693
823
.511
MYR
Malaysian Ringgit
 2.4028 2.3915 2.3949 2.3612
NOK
Norwegian Krone
4.9  4.9086 4.8864 4.9077
PGK
Papua New Guinea Kina
1.581 1.5972
PHP
Philippines Pesos
34.0844 32.8944 31.8249 34.2285
SEK
Swedish Krona
5.4553 5.4978 5.5236 5.4419 5.484
SGD
Singapore Dollars
1.016 1.0391 1.0341  1.0347 1.0223 1.0313 1.0149 1.0149 1.0424 1.0056
THB
Thailand Baht
24.0471 24.113  23.97 23.1032 23.5503 22.8464 24.3101
TOP
Tongan Pa’anga
1.357  1.3561 1.3265 1.2833 1.2952
TRY
Turkish Lira
1.3627 1.3278
TWD
Taiwanese New Dollars
22.2885 24.5463
VND
Viet Nam Dong
15631
.8624
14126
.4372
VUV
Vanuatu Vatu
73.5993 72.4979
WST
Samoan Tala
1.819 1.7952  1.6719 1.7601 1.677 1.705
XPF
French Polynesian Francs
75.28 75.5565  75.54 71.894 74.1345
ZAR
South African Rand
7.5277 7.5567  7.6146 7.4484 7.4618 7.1077 7.6671

As you can see, there isn't one outright winner.  Depending on the currency you want to purchase, and the time at which you are checking the rates, your choice could swing one way or another.  Just because a certain business offers the best rate doesn't mean it is necessarily the best option either, because it could come with high fees that outweigh the rate advantage. Or it may not be suitable because you need to wait for the currency to be ordered, when you are in a hurry to get the money.

Which Form of Payment?

Banks generally charge a 1% commission for changing foreign currency, with a minimum fee.  It's always useful to have some cash on hand before going to another country, but you may want to have another form of payment to avoid carrying large wads of cash around, and for paying for higher value and/or online purchases.  You can, of course, use a credit or debit card linked to your bank account, which is a very convenient option.  But this often comes with high fees for cash withdrawals and currency conversions, which you might be able to bypass by using a multi-currency travel card.  You may also want to use a standalone travel card in case it gets stolen, or to make sure you don't spend too much.


Form of PaymentProsCons
Cash
  • Money is right there; no need to look for an ATM
  • You can request smaller notes when getting your money changed, useful for smaller purchases
  • Cash is accepted everywhere, including at roadside stalls
  • At certain stores, you may go into an express queue if paying by cash
  • Need to collect cash from bank or money exchange location
  • Cannot make online purchases, e.g. top up mobile credit from home
  • No recourse if your money is lost or stolen, or at least it may be difficult to prove how much you had
Credit Card
  • Convenient; no need to plan ahead
  • No need to set aside funds in advance; money potentially earning interest at a bank if not used
  • Can be replaced if lost or stolen
  • May offer rewards for purchases

  • High fees, particularly for cash withdrawals
  • Cannot know exchange rate ahead of time
  • Card may not be accepted for smaller purchases, or merchant may charge a fee for its use

Travel Card
(Multi-Currency Debit Card)
  • Can "lock in" exchange rate
  • Standalone card with no link to your bank account could provide peace of mind
  • Potentially lower fees and/or better exchange rates than credit cards
  • Can be replaced if lost or stolen
  • May offer rewards for purchases
  • Requires research and planning, e.g. understand concept of wallets, must load money before using the card, take steps to avoid fees
  • Complicated fees structure
  • For longer trips, you will want to make sure you have internet access to manage your funds
  • Card may not be accepted for smaller purchases, or merchant may charge a fee for its use

A Closer Look at Travel Cards

I only know of three main travel card options, which I have included in the table of fees and limits below (please check the official websites to confirm these have not changed).  Kiwibank's Loaded for Travel card appears to have the best exchange rate, but is also the only travel card to charge $6 for every ATM withdrawal, and has a higher fee for loading money onto the card, assuming you are loading more than $100. You will not be issued a new card once it expires, so you would need to pay another $12 setup fee for a new one. Air New Zealand's OneSmart card is the only one which is free to obtain and rewards purchases on the card (bonus Airpoints Dollars), but is also the only travel card which does not offer you a secondary card for the same account, free or otherwise [Added 8 May 2013: looks like this may be offered at a later date].  Travelex's Cash Passport has higher limits than the others, though that is not necessarily a good thing.

OneSmart Loaded For Travel Cash Passport
Card type Mastercard Visa Mastercard
Promoted by AirNZ NZ Post Travelex
Issuing Bank BNZ Kiwibank
Fees (changes to OneSmart fees effective from 21 May 2013 highlighted in red below)
Setup fee $0
(you can join Airpoints for free using the promo code JOINAP)
$12 Dependent on agent
Secondary card fee N/A $10 $0 $0
Load/Reload fee - bank transfer $1 $0 1% of the amount loaded, up to $10 $1
Load/Reload fee - via agent $3.95 $4 1% of the amount loaded, up to $10 The greater of 1% of the initial load / reload amount or NZ$10.00
ATM balance enquiry $1 $1 not mentioned
ATM cash withdrawal - in NZ $1.50 $2 $6 $2
ATM cash withdrawal - international $0 $0 for first three withdrawals per month, thereafter NZ$3 or similar values in other currencies $6 $0
Branch withdrawal fee - cash over the counter N/A $6 $10
Currency Conversion Fee - unsupported currencies 2.50% (not charged although listed in fees) 2.50% (enforced) 2.50% 5.95%
Currency Conversion Fee - insufficient funds in wallet 0.00% 0.00% 5.95%
Monthly account fee $1.95 unless money loaded, or no money in NZD wallet $1, even if money loaded. Fee taken from other wallet if insufficient NZD $0 $0
Monthly Inactivity fee $1.95, after 3 months $0 (now covered by monthly account fee) $1, after 12 months $4, after 12 months
Email alerts fee $0 $0.05 N/A
TXT alerts fee $0.10 N/A N/A
TXT service fee - balance enquiry $0.10 $0.50 N/A
Card replacement fee $12.95 $10 $10 $0
Express delivery fee $25 $15 - $30 N/A
Paper statement fee $9.95 $10 N/A N/A
Disputed transaction fee $9.95 $10 $15 not mentioned
Closure/Transfer fee $9.95 $10 $15 $10
Limits
Max load amount $10,000 $9,500 $25,000
Max load per day N/A $9,500 $25,000
Max balance across all currencies $10,000 (online verification), $25,000 (verification in person) $75,000 on application $20,000 $75,000
Max withdrawal amount $1,000 $1,000 N/A
Daily max withdrawals and purchases N/A $5,000 $15,000
Daily cash over the counter limit N/A N/A $400
Daily max ATM withdrawal $1,000 $2,500 $3,000

[Added 11 May 2013:

My Latest Experience with the OneSmart Card

Cash vs. OneSmart

On 29 April, I was quoted a rate of 6.5251 for changing HKD cash at TSB (this rate remains active until the next morning). Since this was much better than the rate on OneSmart (which was around 6.37), and I always like to have some cash on hand, I walked in to their Queen Street branch and changed another 6,000 HKD, even though I had already loaded money on my OneSmart card. This cost me 928.73 NZD: 6000 / 6.5251 = $919.53 in straight currency exchange, plus 1%, or $9.20 in commission.  You could say that this had an effective exchange rate of 6000 / 928.73 = 6.4604. I left my money as NZD on OneSmart, in case I chose not to spend it overseas, but on groceries at home instead.

On checking in to a hotel a day later, I was given the option of paying in cash, or by card.  The OneSmart exchange rate at the time was 6.3531, so a room costing 700 HKD would cost 700 / 6.3531 = 110.18 NZD.  Since I would earn 1% of the value spent overseas, or $1.10, in Airpoints Dollars, I calculated the effective exchange rate as 700 / (110.18 - 1.10) = 6.4173.  Not as good as the rate I had from TSB.  I chose to pay in cash, which was a good thing, as we ended up leaving the hotel early.  Getting payment back in cash is much better than having a pending transaction trapped in your OneSmart card, because you can spend the money again immediately.

The exchange rate on OneSmart did go up to 6.40xx a couple of days later, which would have yielded an effective exchange rate of something like 6.4641 for overseas purchases (but not ATM withdrawals).

At the start of my trip, I was able to have much better exchange rate from a bank than from the OneSmart card.  However, if the exchange rate was going to keep going up, using the OneSmart would have allowed me to change money at a later point in time, when the exchange rate was better (but, not having prophetic powers, it could have been even worse as well).

Credit card vs. OneSmart - purchases in-store while overseas

The thing with credit card exchange rates is that they are not published anywhere, so it is difficult to know in advance whether they are worth using, other than for the obvious convenience factor.  To compare the rate of my Visa credit card against OneSmart, I looked at transactions that were made at a similar time.

While I was in Hong Kong last week, I went clothes shopping (the shops were open till midnight or 1am!).  At one shop, I made the payment on my Visa credit card at 23:20 on 5 May.  The 998 HKD was converted with an exchange rate of 6.5831 to 151.60 NZD.  On top of this, I had to pay an Offshore Service Margin of 2.1%.  I calculated this to be 0.021 * 151.60 = $3.1836, but this was rounded up to $3.19 in my statement.  In total, this purchase cost me 151.60 + 3.19 = NZ$154.79, which I considered as having an effective exchange rate of 998 / 154.79 = 6.4474.  (I am not considering rewards in this section, as I am assuming credit cards and OneSmart both offer rewards of 1%, though this may be different depending on the type of credit card you have.)

For a smaller purchase across the road, I used my OneSmart card at 23:58, also on 5 May.  This time, a 179 HKD purchase was converted to 28.18 NZD, giving an effective exchange rate of 179 / 28.18 = 6.3520.  Even without further fees, this was worse than using the credit card.

To be sure, I checked again on another day, when I had purchases on the two cards within a couple of hours  of each other.  This time, what I call the effective exchange rate was 6.4378 and 6.3910 for Visa and OneSmart respectively.  Again, the Visa credit card had a better exchange rate, even after taking the Offshore Service Margin into account.  If you consider how much easier it is to use a credit card (no need to load money in advance) and the fact that you have a one month grace period before you have to pay that debt off, the credit card is superior these days.

Credit card vs. OneSmart - obtaining cash from ATM while overseas

So what if you have run out of cash, and need some more?  Using the same rates as above getting 1,000 HKD in cash from an ATM using a credit card would cost you 1000 / 6.4474 = 155.10 NZD using your Visa card, and you would need to pay a fee of $7.50, so a total of 155.10 + 7.50 = $162.60.  Don't forget that for cash advances, interest is payable immediately, rather than having the one month grace period that purchases offer.

In contrast, using your OneSmart, the same amount of foreign currency would cost you 1000 / 6.3520 = $157.43.  With the new fees kicking in from 21 May, you would have to pay an extra 20 HKD for the international withdrawal if this is your fourth withdrawal in the month.  In this case, it would cost you 1020 / 6.3520 = $160.58.

In either case, the OneSmart is better for overseas cash withdrawals than my Visa credit card.

---

In the past, I have found the OneSmart to be an excellent solution for travelling with less cash.  However, as various people have pointed out, its exchange rates are poorer these days, and its fees are changing as of 21 May 2013.  While the OneSmart is still good for withdrawing cash overseas, for a shorter trip to a developed country, I would now rely on getting cash out from a bank in advance, then making purchases on my normal credit card, but perhaps for a longer trip to a destination where you feel less comfortable with carrying cash and where credit cards are not widely accepted, you may choose to go for a travel card solution.
]
As usual, different options each have their own advantages and disadvantages.  You will need to evaluate your intended spending behaviour to find out what would work best for you.  Good luck, and happy travels!

Sunday, November 11, 2012

Money Matters: Drawbacks of the Air New Zealand OneSmart Card

[Added 28 March 2018: This post is very old. OneSmart now has instant debit loads, for instance.]

In a previous post, I compared using the Air New Zealand OneSmart card as a travel wallet against other options, such as changing cash at a bank, and getting money out overseas using your credit card.  I found that this branded Mastercard debit card was a good choice, with no commission fees, no ATM withdrawal fees while overseas, and no offshore service margin/currency conversion fee if changing between supported currencies. Although I do still recommend using this card on your holiday, it does come with its share of frustrations as well.

Drawback 1: You can only spend what you have in your account.

The most obvious disadvantage of the OneSmart card is that, unlike a credit card, you have to plan ahead.  Debit cards work like prepaid phone cards: you need to put money on it before you can use it.  If you only have $29 in your OneSmart account, and you want to buy a $30 item, then—surprise, surprise!—that transaction will be declined.

What might be unexpected behaviour is that if you do not have enough money in the local currency wallet, but you have money tucked away elsewhere (e.g. you are making a purchase in Europe, and you don't have enough money in your EUR wallet, but you do have further funds in a USD wallet), then an automatic currency conversion from the other wallet will occur to allow your transaction to proceed.

What to do about it: Make sure you have loaded more than enough money for your use.  Yes, that does mean planning ahead.  You could also keep a credit card handy.  There is the issue of what to do with your leftover money when you have loaded too much - see the solution to Drawback 7 below.

Drawback 2: It takes a business day for the money you have transferred to show up on your OneSmart account.

If you transfer money to your OneSmart account on Friday night NZ time, chances are you won't be able to access that money until Tuesday morning.  That's waiting three and a half days before you can use it.

What to do about it: Keep an eye on what day of the week it is and how much money you have left to spend.  Top up if you have to before you hit the weekend, or you could find yourself using your credit card more than you intended to.

Drawback 3: The transaction history page is difficult to understand.

If you check OneSmart online (and I recommend that you do so regularly), you will see your current balance, your pending transactions and your transaction history.  Technically, you have everything you need: how much each transaction was, in what currency, and whether it was for loading cash, an ATM withdrawal, or a purchase, etc.  But it can be confusing for a number of reasons:
  • You can only see your current balance, not what you had in each wallet when a transaction was made.
  • Transactions can appear out of order (this is also true on your normal credit card, but there you are shown a running balance).
  • Each transaction is shown with a processing date, but this is not necessarily the date when you made the transaction.  Often you will find multiple transactions from the same day being processed at the same time.
  • Transactions can change currency from what was shown when they were pending, e.g. if you made a purchase in Euros, but had no money in your EUR wallet, the money will be converted from the first wallet you have money in, so the pending transaction could be shown in NZD (in this case, you will not be able to see the price you paid in Euros while the transaction is pending).  If you transfer money to your EUR wallet before the transaction is processed, the final transaction will be shown in EUR.
  • The same purchase can appear as multiple transactions.  I once had a payment split across three different currencies, because I did not have enough money in the first two wallets
  • If an automatic currency conversion occurs, you are shown what amount in the original currency was converted to what amount in the final currency, but you don't get to see the exchange rate.
  • Often an automatic currency conversion is not exact.  You end up paying a few cents more or less, leading to your balance occasionally showing something like EUR -0.03.  For instance, I withdrew 100 pounds from an ATM in London when I had no funds in my GBP wallet.  To pay for this, OneSmart automatically converted 200.98 NZD to 100.03 GBP.
What to do about it: If keeping a tab on your money in each wallet is important to you, make your own spreadsheet of running totals. I found this especially useful when I began using multiple currencies and suspected errors in the calculations (it turns out I had simply spent more money than I realised). It also allowed me to make notes on transactions when the default descriptions were not very enlightening.

Drawback 4: If you present your OneSmart card for authorisations and deposits, that money will be locked from use.

For deposits (e.g. on a rental car) and authorisations (e.g. for a hotel booking, in case you don't turn up), credit cards have an advantage, because you can still continue on as if nothing had happened.  When you have returned the car or shown up for your hotel stay, the pending transaction is simply cancelled.

On debit cards like the OneSmart, however, these transactions will put a certain amount of money on hold.  And simply returning the car or paying for your hotel does not mean you have access to those funds again.  You have to wait for the pending transaction to expire, which, according to a hotel that authorised the first night's stay without really warning me, would take 10-14 working days (that's 2-3 weeks of not being able to use the money, by which time your holiday might be over!).  The actual pending transaction I saw in my OneSmart account was marginally better, expiring after 9 days.

What to do about it: Watch out for authorisations and deposits, i.e. where merchants ask for your credit card details with little intention of taking the money.  Where these are requested, give them your normal credit card instead.  You can still pay for your hotel or car hire using your OneSmart though.

Drawback 5: Credit and debit cards do not work everywhere.

The OneSmart card has served me well.  It has worked with every ATM I have used it with, and I have never been charged fees by an ATM provider either.  However, a workmate was not so lucky.  He loaded his OneSmart up with all the money he planned to use, and went to Japan with no cash.  Too late, he discovered that Japan is a very cash-based society, and most ATMs there do not accept Western credit cards, including Visa and Mastercard; ones that display the logo often work only with credit cards issued in Japan.

What to do about it: This is not a problem with the OneSmart card, but with foreign credit cards in general. Do your homework. Research your destination ahead of time, and bring some cash with you just in case.  Eventually, my workmate worked out that in Japan he could get money out at ATMs in the 7-11 convenience stores between certain hours, and this seems to be true of ATMs in postal offices as well. [Added 27 January 2013: having returned from Tokyo recently, I can say that 7-11 ATMs work even at 9pm at night, whereas the ATMs at another convenience store (Lawson's) clearly stated that foreign credit cards are not accepted.  A random ATM I found at a subway station let me get out as little as ¥1,000 (around NZ$15), which was better than the 7-11 ones which had a minimum of ¥10,000 (~ NZ$150).]

Drawback 6: Those pesky fees...

As with all banking products, there are fees involved with using your OneSmart card.  I think they are entirely reasonable compared to, say, using your normal credit card overseas, but you should still acquaint yourself with them so you can avoid them as much as possible. [Added 8 May 2013: The new fees schedule effective 23 May is less attractive than it used to be.  I take another look in a newer comparison.] [Added 22 May 2013: And I vent by displeasure at the lack of notice given for the changes.]

What to do about it: Read through the OneSmart fees schedule. To avoid the Monthly Account fee, do not leave money in your NZD wallet for more than a month.  To avoid the Account Inactivity fee, make a transaction at least every three months, for instance by moving a small amount of money from one wallet to another.  Don't query your balance at an ATM, but rather check it online.  And so on and so forth... [Added 22 May 2013: The new changes removes the Inactivity Fee, but applies a reduced Monthly Account Fee regardless of where your money is sitting, so you cannot avoid it simply by moving your money to a foreign currency.]

Drawback 7: You can't transfer money back to your bank account.

The thing that people seem to be the most surprised or frustrated by, when they first use their OneSmart card, is that when they return home from their holiday, there is no easy way to get the leftover money out again.  You can't transfer the money back to your bank account.  There's a fee for getting cash out at an ATM in New Zealand using your OneSmart, and you can't withdraw less than $20 anyway.  And unless you are going to use it soon, your money is wasting away there, not collecting interest, not to mention there is the potential for fees to be charged unless you do something about it.

What to do about it: Depending on your situation, you could deal with your leftover money in a number of ways...

1) No trips planned anytime soon:
After your holiday, use your money up with your OneSmart card wherever you normally use your credit card.  Use it to pay for your groceries, your petrol, your online purchases, dinners with your friends.  At the Countdown supermarkets, the self-service kiosks have a "split payment" function, where you can specify the exact amount to charge to a card, so you don't even need to go to the trouble of trying to make your items add up to a particular number.

2) Friend is about to go on holiday:
Alternatively, if you have a friend who is about to go on holiday, who is planning to use their OneSmart card, you could give your money to them (click on the orange "Send Money" button underneath your balance in the top right corner).  All you need to know to do this is either their OneSmart account number or their mobile number. This not only saves you the trouble of having try to use the money up yourself, it also saves your friend the (pretty minimal) $1 load fee.  Currently, there is no fee for OneSmart account to OneSmart account transfers done online.

3) You are planning to go overseas again soon-ish:
If you purchased foreign currencies at a very good exchange rate, or if you can't be bothered getting your money out because you are planning another trip soon, you can, of course, opt to simply let your money sit in your OneSmart account.  See my solution to Drawback 6 about avoiding fees.

Drawback 8: You probably know more than the customer service staff.

It's sad but true: half the time I have rung up the customer service centre, someone has given me the wrong information.  This is true of many other organisations too, of course, so if I'm not in a hurry, I tend to write them an email.  It gives them time to think, you don't have to spend hours on the phone, and you have a written record of what was discussed.

Here are some untruths I have been told over the phone...

  • Myth 1: To avoid the Account Inactivity Fee when you have $0 in your NZD wallet but a positive balance in another wallet, you need to load some money at least once in a three-month period.  Reality: You just need to make a transaction, whether that is loading cash, purchasing goods or changing money from one wallet to another.
  • Myth 2: If you see a pending transaction disappear without going onto your transaction history, you are no longer liable for the purchase you have made.  Reality: In the unlikely event that the pending transaction expires before it has cleared, it looks as though the value of your purchase is returned to you and there is no record of the transaction visible anymore.  You can spend the money that you see (including the amount that was released from the pending transaction), but when the expired pending transaction finally clears, your account will go into a negative balance.  Unfortunately, if a currency conversion had to be done automatically (e.g. you made a purchase in NZD but you only had money in your HKD wallet), then the exchange rate will be calculated anew, possibly using a less favourable rate.
  • Myth 3: You would have received an email letting you know when your account was activated.  Reality: I keep all my important email, and I never received such a notification.  I did however work out my activation date based on when I presented my ID at an Air NZ Holidays Store as part of the activation process, and the fact that I had managed to load money into my account two days later.  It turns out you don't need to know what your activation date is anyway, as you will see in Myth 5.
Amazingly, what you read on their official website might not be true either.
  • Myth 4: You can only load up to $1,000 at a time. Reality: This has now been corrected to $10,000 on their FAQ page, but for the best part of a year, their old FAQ page displayed the mistaken value.
  • Myth 5: You will be charged a Monthly Account Fee if you have not loaded at least NZ$500 in the last month, and it is now the end of your activation month.  According to footnote 1 in the fees page, "month" means "each period of one month starting on the date you Activate your OneSmart Account. For example, if you Activated your OneSmart Account on the 7th of the month, you would need to load NZ$500 or more between the 7th of this month, and the 6th of the next month to qualify for the Monthly Account fee waiver." Reality: The Monthly Account Fee appears with the description "Subscription Fee" in your transactions. I was charged this fee on the 28th, and challenged it as my activation date is actually on the 16th, and I had made sure I had no money in my NZD wallet, until a refund came through just on the day the fee was charged. I had to fight for a refund, and a CSR tried to convince me that the fee is charged in monthly periods from the Account Creation Date (which he claimed was on the 30th) rather than the Activation Date.  I have subsequently been told by a different CSR that all accounts are charged on the 28th, regardless of when you activated.
  • Myth 6: There is a 2.5% currency conversion fee charged for unsupported currencies. Reality: I have not yet seen this charged [Added 8 May 2013: however this fee will be applied in the future according to the new fees schedule].

What to do about it: You can take the conservative approach, e.g. make sure you don't keep money in your NZD wallet for more than a month without loading more money, or you can learn how things work by trial and error, as I did.  If there is a problem (e.g. you were charged a fee when you shouldn't have been), then write an email to the help desk if you are happy to wait for a response.  Otherwise, make sure you have all the relevant information when you ring up, so you can argue your case effectively.  If that still fails, try calling again later.  A different CSR may be more clueful.

---

So was it worth it using the OneSmart card, given the issues I've mentioned above?  Well, I can't tell you exactly how much I've saved, but from my twenty cash withdrawals from overseas ATMs alone, I have avoided paying 20 x $7.50 = NZ$150 in fees already (yes, that credit card cash advance fee has gone up at my bank!)  True, I would have gotten cash out less often otherwise, but I liked the fact that the OneSmart card made me feel free to withdraw smaller amounts of money more frequently. [Added 8 May 2013: according to the new fees schedule, only 3 international ATM withdrawals per month will be free.] Whether the extra time investment you need to use the OneSmart card is worth the savings it provides, is up to you to decide for yourself.  Happy travels!
Related Posts Plugin for WordPress, Blogger...